What a Builder's Mortgage Rate Is Worth on a Redmond Townhome
November 19, 2026
November 19, 2026
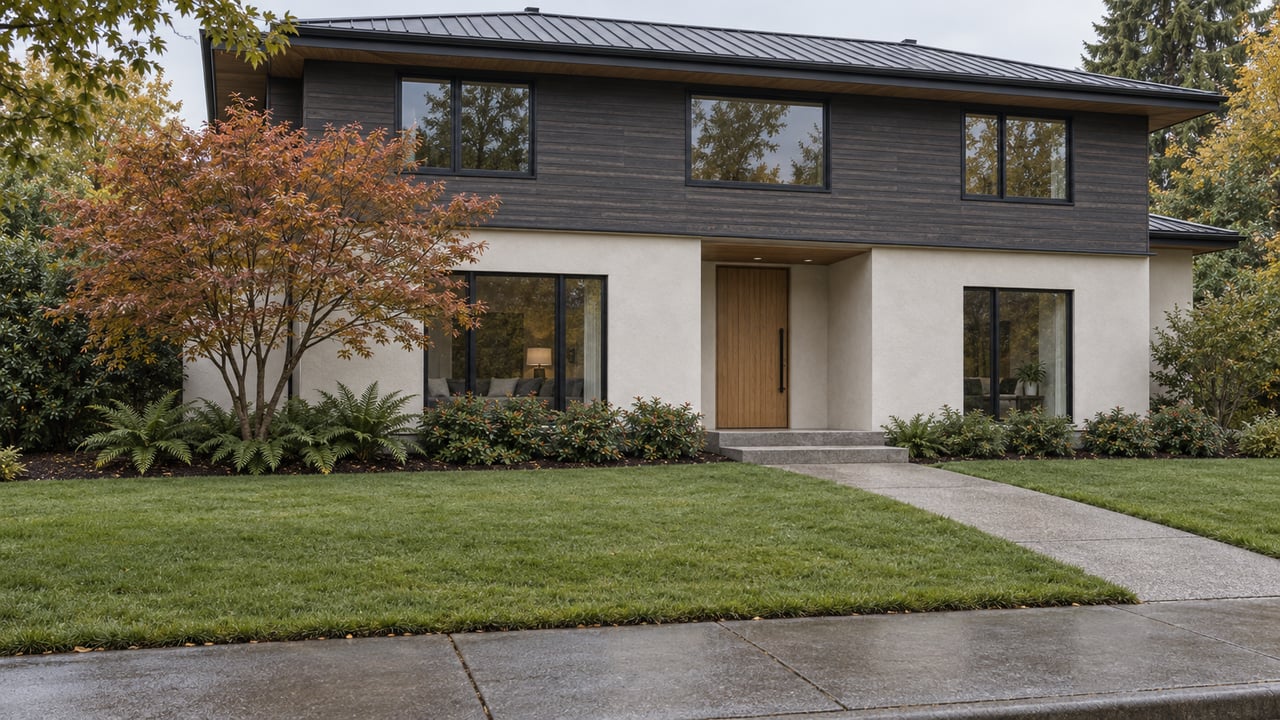
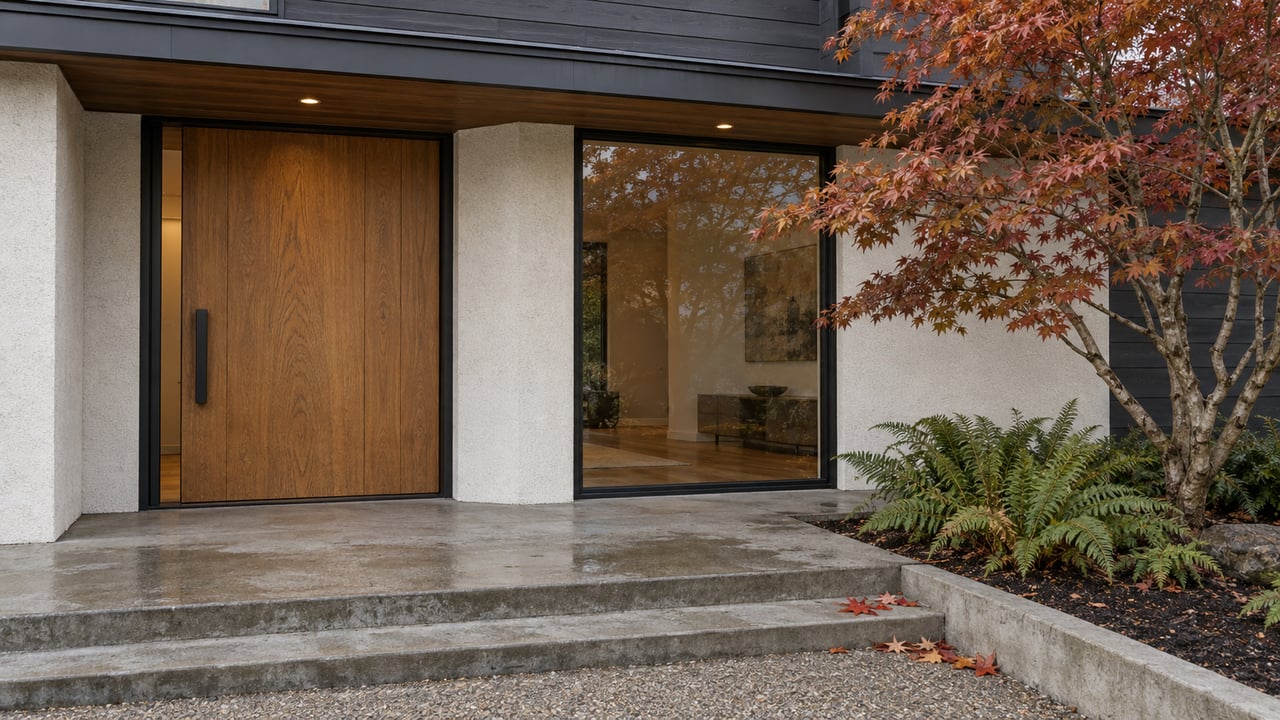
Two Redmond new-construction communities have homes for sale near $900,000. At Willows 124, Tri Pointe Homes' townhome community at 13880 NE 123rd Way, plans start at $899,900. One move-in-ready townhome is listed at $939,900. In Rose Hill, Toll Brothers has one quick-move-in home left at Canopy Cottages: three bedrooms and 1,259 square feet for $899,000.
Those prices look like any other listing. On new construction in Redmond this fall, though, the list price is not where builders are giving ground. They are giving it on the mortgage rate, and for a buyer comparing a new build with a resale, the rate is worth more than most of the price cuts a resale seller would consider.
The incentives make sense once you see how the fall went in NWMLS area 550. That is the MLS reporting area for Redmond and Carnation, which is close to Redmond but not the same as the city limits. In October 2026 the median sale price for single-family homes there was $1,180,000, down 21.3% from $1,500,000 in October 2025. Over the same comparison, active listings went from 127 to 169 and pending sales fell from 53 to 36. Inventory reached 4.23 months at October's sales pace.
Homes are also taking longer to sell. Single-family homes that closed in area 550 in October averaged 79 days on market, up from 49 a year earlier. New construction has waited longest. At the end of October, area 550 had 25 active new-construction listings with a median asking price of $859,995 and an average of 270 days on market. A year earlier that average was 190 days. Only seven new-construction homes closed in the area in October, and they averaged 260 days on market.
Financing costs explain part of the slowdown. Freddie Mac's 30-year fixed average was 7.11% for the week of November 12, 2026. That was the fourth straight weekly decline, but the rate is still well above the 6.24% average of a year earlier. The Northwest Multiple Listing Service's October report says rates peaked at 7.40% in the weeks of October 8 and October 15. It also says October's 4.41 months of inventory across its whole service area was the highest for any October since at least 2014.
When a builder's homes have been listed for most of a year and buyers are paying more than 7%, the builder can cut the price or lower the rate. Right now, Redmond's builders are mostly lowering the rate.
Tri Pointe is advertising a conventional 30-year fixed 1/0 buydown on select move-in-ready homes at Willows 124. The rate is 3.99% for the first year and 4.99% for years two through thirty, with an APR of 5.645%. The terms require a purchase agreement signed between October 28 and December 31, 2026, at list price, with financing through Tri Pointe Connect. The builder says the offer can change or end without notice.
The "at list price" condition matters most. The incentive is in the loan, and the price on the contract stays at the asking price.
Toll Brothers is advertising a regional 30-year fixed rate of 5.49%, with a 5.76% APR, on select quick-move-in homes. It requires an agreement signed on or after October 8, 2026, and closing by January 8, 2027. The offer covers only "select" homes, so ask Toll's sales center whether the remaining Canopy Cottages home qualifies before you count on it.
Canopy Cottages also shows the other approach. In a January 27, 2026 announcement, Toll said five of the community's 26 homes remained, ranging from 1,259 to 1,488 square feet, and that move-in-ready and quick-move-in homes were "priced from $1.249 million." The one home listed there now is $899,000 for the smallest floor plan. Homes in a community differ in lot, finishes and features, so this is not an exact before-and-after on one house. It does show that the starting price at Canopy Cottages has come down a long way this year.
A buyer comparing a builder's rate with a resale needs both expressed in the same unit, and the monthly payment works best. The table below uses a $900,000 purchase with $180,000 down and a $720,000 loan. It shows principal and interest only and leaves out property tax, insurance and any HOA dues. The last column shows what a resale at 7.11% would have to sell for to produce the same payment with the same $180,000 down.
| Rate on a $720,000, 30-year loan | Approx. monthly principal and interest | Resale price at 7.11% with the same payment |
|---|---|---|
| 7.11% (Freddie Mac average, week of Nov. 12, 2026) | $4,844 | $900,000 |
| 5.49% (Toll regional offer) | $4,084 | about $787,000 |
| 4.99% (Tri Pointe, years 2 to 30) | $3,861 | about $754,000 |
| 3.99% (Tri Pointe, year 1) | $3,433 | not comparable, since the rate lasts one year |
These figures are rounded estimates for comparison and are general information only, not financial advice. Rates, terms and eligibility change, so confirm your own numbers with a lender before you rely on them.
At 4.99%, the monthly payment on the $900,000 townhome is about $983 lower than the same loan at the 7.11% average. A resale seller would have to cut the price to roughly $754,000 to match that payment, which is about $146,000 or 16% off. The Toll rate is worth less but still a lot: about $760 a month, or a resale near $787,000.
Most resale sellers in area 550 will not cut 16%. Even this fall, with the area's single-family median down about a fifth from a year earlier, that median is measured across all homes sold. It does not mean a given seller is willing to take $146,000 off their own listing. A resale buyer who negotiates $30,000 or $40,000 off is still paying a payment much closer to the 7.11% line than to the builder's 4.99% line.
The math above favors the builder, but four things narrow the gap.
First, the builder rate comes with conditions. Tri Pointe's offer requires its affiliated lender and a full-price contract. A buyer who would rather use their own lender, or who expected to negotiate the price as well, is weighing a different trade.
Second, the deadlines are close. The Tri Pointe signing window closes December 31. Toll requires closing by January 8, 2027. Both only make sense for a buyer who can be ready that quickly.
Third, the product is different. Willows 124 is a townhome community that the builder places between Redmond Town Center and Totem Lake, with connections to the Redmond Central Connector, the Sammamish River Trail and the Cross Kirkland Corridor. Canopy Cottages is 26 two-story homes around shared green space in Rose Hill, with a clubhouse and event lawn, and is part of the Lake Washington School District. A buyer who needs a detached house with a yard on Education Hill is not shopping the same homes, whatever the payment. Our earlier comparison of Redmond condos and townhomes covers those differences in format.
Fourth, a lower rate has to last to be worth its full value. The table assumes the buyer keeps the loan for years. If rates fall far enough that a resale buyer refinances, the gap shrinks. Freddie Mac's average has fallen four weeks in a row since the October peak, but no one can know how far it will go.
If you own a townhome or a smaller house in the same price range near Willows 124 or Rose Hill, your buyer is likely to tour a builder's model with a 4.99% rate attached. Your listing is competing against that monthly payment as well as the asking prices of nearby resales.
That helps explain why resales took longer this fall. Area 550's average market time for closed single-family homes rose from 49 to 79 days between October 2025 and October 2026, and pending sales fell by about a third. A seller can still compete. The most useful starting point is to look at your listing the way a buyer will: by monthly payment, next to the builder's offer. A current home valuation is the place to start, read next to what the nearest builder is offering this month.
For buyers, the useful number in a Redmond new-construction listing this season is the payment after the builder's incentive. Compare it with the payment on the resale you were also considering, using the same down payment. The Redmond homes for sale page has both kinds of listings. For background on how different parts of Redmond have moved this year, see our Redmond light rail market analysis.
Does a lower builder rate mean the home is overpriced? Not necessarily. The incentive comes through the loan, and the contract price stays at list. Compare the monthly payment, the home itself and nearby resales together before you decide what the price is worth.
Do these offers apply to every new home in Redmond? No. Tri Pointe's buydown covers select move-in-ready homes at Willows 124, and Toll's 5.49% rate covers select quick-move-in homes. Each has its own signing and closing deadlines.
Are the NWMLS figures for the city of Redmond? They cover NWMLS area 550, which includes Redmond and Carnation. They follow the Redmond market closely but are not limited to the city.
Whether you are weighing a builder's rate against a resale on the next street, or getting your own Redmond home ready to compete with one, we would be glad to work through the payment math with you, one home at a time. Reach out to Craig Northwest Homes to get a free home consultation before the year-end deadlines arrive.
Stay up to date on the latest real estate trends.